In the ever-evolving landscape of finance and investment, finding effective strategies to diversify one's portfolio has become an essential goal for astute investors. One such strategy that has gained significant traction in recent years is Self-Managed Superannuation Fund (SMSF) borrowing.
This powerful financial tool enables individuals to leverage their SMSF to invest in a wider range of assets, including property and other high-yield ventures. By utilizing SMSF borrowing, investors can unlock a world of opportunities and potentially amplify their returns, all within the framework of their superannuation fund.
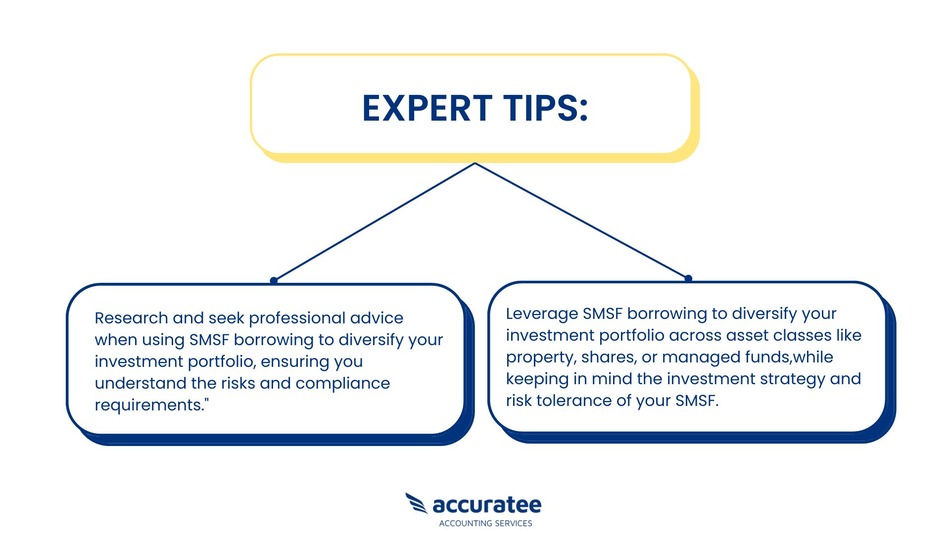
In this blog post, we will explore the concept of SMSF borrowing, delve into its benefits and risks, and provide you with valuable insights on how to make the most of this strategy to diversify your investment portfolio.
Key takeaways
- SMSF borrowing allows trustees to leverage their superannuation savings for a broader range of investments.
- Risks associated with SMSF borrowing include default, market volatility, interest rate fluctuations, regulatory changes, asset liquidity, and personal liability.
- Diversification is crucial for managing risks and maintaining a balanced investment approach.
- SMSF borrowing enables investment in diverse assets like property and shares for potentially higher returns.
What are SMSF borrowings?
SMSF borrowings, also known as limited recourse borrowing arrangements (LRBA), refers to a specific exception under the super law that allows self-managed super fund (SMSF) trustees to borrow money. Normally, borrowing is prohibited for SMSFs, but LRBA enables trustees to obtain loans from third-party lenders. The trustee then uses the borrowed funds to purchase a single or a group of identical assets with the same market value. These holdings are held in a separate trust.
The SMSF trustee receives any investment returns generated by the asset. However, in the event of a loan default, the lender's rights are limited solely to the holdings held in the separate trust. This means that the lender cannot access other holdings held within the SMSF. This arrangement provides a level of protection for the SMSFs remaining holdings, reducing the overall threat for the fundings.
What are the specific circumstances in which your SMSF fund is allowed to borrow money?
Your fund can only borrow money in specific situations. These situations include:
- Borrowing money for up to 90 days to pay members' benefits or cover outstanding surcharge liability. However, the amount borrowed cannot exceed 10% of your fund's total assets.
- Borrow money for up to seven days to settle security transactions, as long as the borrowing is within 10% of your fund's total asset. You can only borrow for this purpose if it is unlikely that borrowing would be necessary at the time of the transaction.
- Borrowing through instalment warrants or limited recourse borrowing arrangements that meet certain conditions.
Key benefit of SMSF recourse borrowing
An SMSF limited recourse borrowing arrangement offers several key benefits. Here are a few of them:
Leverage your superannuation savings:
SMSF borrowings allow you to leverage your superannuation savings for investment purposes, enabling your fund to acquire a beneficial interest in an asset it may not otherwise afford. This could include a business premise that you own or operate from. Despite not being the legal owner, your SMSF is entitled to receive all income, such as rental income, and any capital gains from the asset.
Tax concession:
There are tax concessions associated with this arrangement. Investment income received by your SMSF, including income from assets acquired through limited recourse borrowing, is taxed at concessional superannuation rates. This can result in considerably lower tax rates than owning the asset personally or under a different structure. If the income supports superannuation income streams, it is exempt from tax in your fund.
Asset protection:
Acquiring assets through limited recourse borrowing arrangements may provide enhanced asset protection. Superannuation assets, including those with a beneficial interest, are generally protected against creditors in case of bankruptcy. Structuring acquisitions in this manner can offer greater asset protection benefits.